Nightly Market Digest
Wednesday, October 21, 2026
Dow Jones 52,856.09 +0.69%S&P 500 7,757.17 +0.58%Nasdaq 26,702.86 +1.05%Russell 2000 2,781.02 +0.27%VIX 16.67 -3.70%Gold 4,152.80 +0.25%WTI Crude 97.73 -0.09%
Wall Street secured a solid midweek close on Wednesday, fueled by renewed artificial intelligence optimism and resilient corporate earnings. The tech-heavy Nasdaq paced the gains, jumping 1.05% to finish at 26,702.857, while the Dow Jones added 0.69% to reach 52,856.09. The S&P 500 rose 0.58% to 7,757.17, and the Russell 2000 ticked up 0.27% to 2,781.021, with market anxiety cooling as the VIX shed 3.70% to settle at 16.67.
Sectors in focus
- Healthcare takes the lead: Investors rotated heavily into medical and biotech names to secure steady cash flows amid tech volatility. Services-Health Services (+3.65%), Hospital & Medical Service Plans (+3.62%), and Pharmaceuticals (+3.58%) dominated the tape, pushing the S&P Health Care Index to a record high.
- Tech and AI stay hot: Super Micro Computer's massive $4B guidance raise to $18.5B-$19.5B and SpaceX's 161% revenue surge to $14.6B revived AI enthusiasm. Meanwhile, Meta posted Q3 EPS of $3.83 (up 265% YoY) and $64.6B in revenue, digesting a hefty $18.59B teen mental health settlement.
- Construction and energy lag: Heavy construction (-1.27%) and pipeline construction (-2.06%) struggled as builder confidence plunged to a 14-year low and pending home sales dropped 7%. Drilling Oil & Gas Wells also slipped 1.40%, with WTI crude inching down 0.09% to 97.73. Oil stabilized in the $98 to $102 range following a 3.06M barrel EIA inventory draw and hopes for US-Iran diplomatic progress. Safe-haven Gold managed a slight 0.25% gain to 4,152.8.
On the radar
- October 22: Tesla (TSLA) Q3 earnings conference call following its post-market Wednesday release.
- October 27-28: The FOMC Meeting, culminating in Wednesday's interest rate decision and press conference, alongside the US Metropolitan Area Employment report.
- October 29: A critical macro session featuring the September PCE Price Index, Q3 GDP (Advance Estimate), and Personal Income/Outlays data.
Market sectors
Upcoming earnings
LRCX Oct 21 (after close)TXN Oct 21 (after close)TMO Oct 21 (before open)IBM Oct 21 (after close)ABT Oct 21 (before open)T Oct 21 (before open)CME Oct 21 (before open)ELV Oct 21 (before open)MCO Oct 21 (before open)UAL Oct 21 (after close)NTRS Oct 21 (before open)CCI Oct 21 (after close)
Today's top bullish signals — top 5
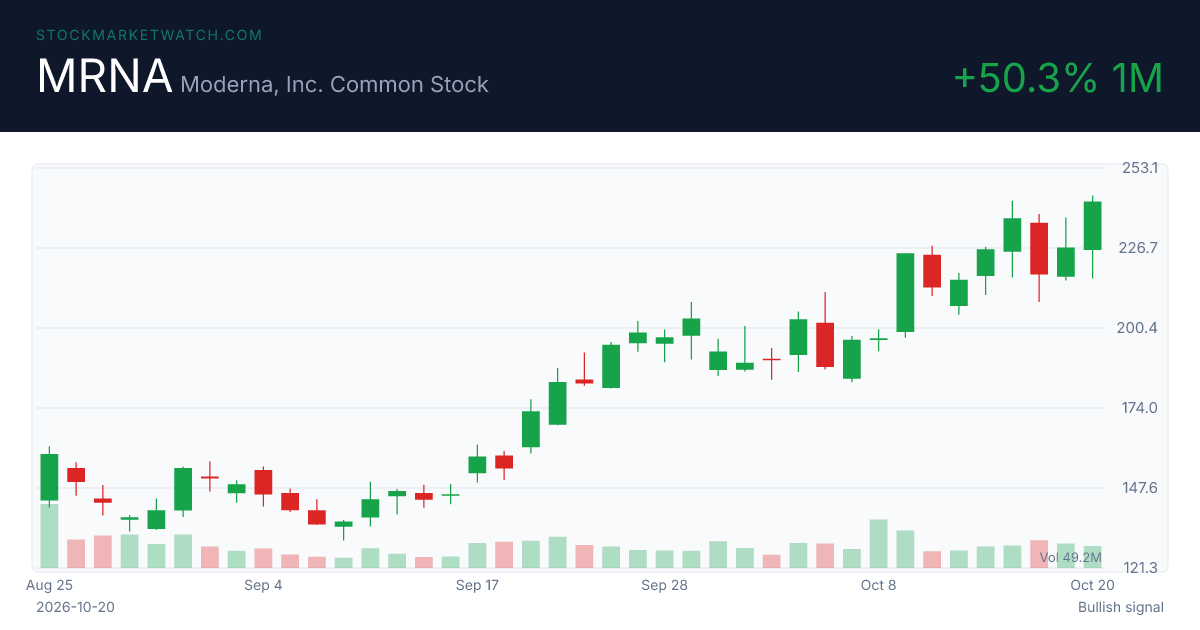
Short squeeze setups — tonight's top 5
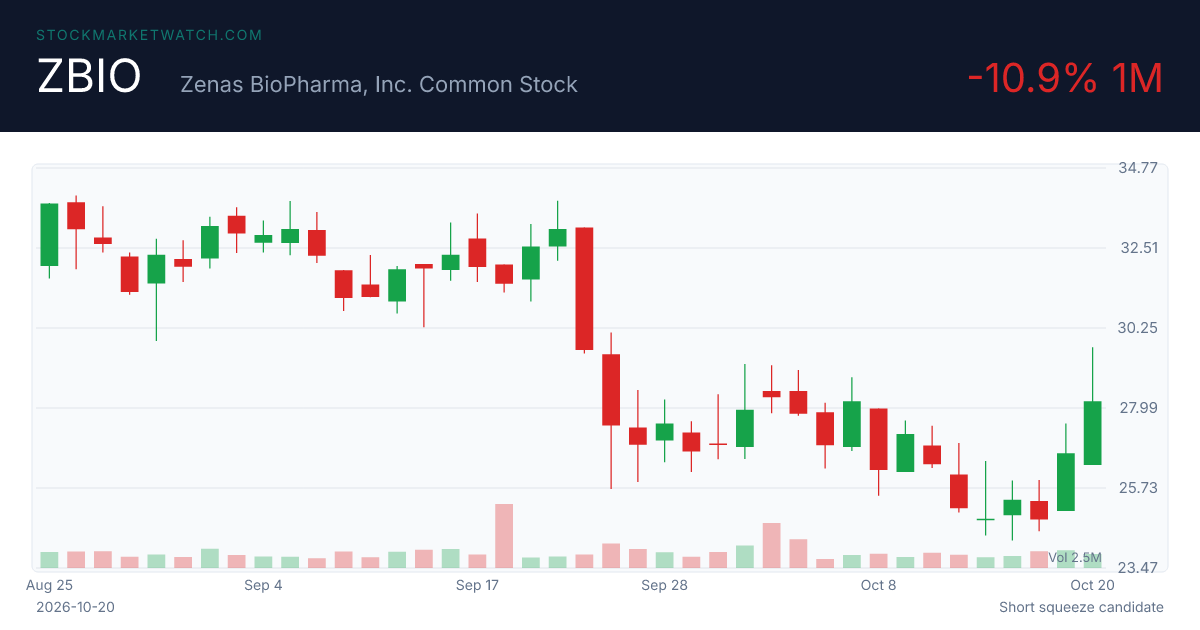
| # | Ticker | Company | Readiness | Short float | Days to cover |
|---|---|---|---|---|---|
| 2 | TNGX | 82 | 32% | 12.5 | |
| 3 | RLAY | 80 | 30% | 12.6 | |
| 4 | PLSE | 79 | 18% | 5.6 | |
| 5 | PRME | 78 | 34% | 8.4 |
View all short squeeze candidates →
Theme turnarounds
| Theme | Net flip | Bull / Bear | Names flipping bullish |
|---|---|---|---|
| Insurance (149) | +13.40% | 13% / 0% | AAME, AMSF, AON, AXS, CINF |
| Longevity & Aging (114) | +5.30% | 5% / 0% | ELS, MFC, NVO, VTR, WELL |
| Real Estate & REITs (264) | +5.30% | 6% / 1% | CIGI, EGP, ELS, EXR, JOE |
| Homebuilding & Housing (80) | +5.00% | 8% / 3% | AMRZ, ESNT, FERG, JOE, LPX |
| Consumer Brands & Retail (320) | +4.70% | 6% / 2% | BROS, CAVA, CLX, COCO, DPZ |
| Oil & Gas (264) | +4.50% | 8% / 4% | DKL, DMLP, DVN, ENB, GLP |
The day's top movers
Today's after-hours movers
Top themes today
Launch & Space Exploration +7.72%Satellite Communications +7.64%Satellite Networks & Connectivity +7.52%Digital Payments & DeFi +7.24%Identity & Access Management +5.71%Prime Contractors & Platforms +4.84%Edge Computing Infrastructure +4.84%DevOps & IT Management +4.66%